Transparency and expertise are needed to defrost Russia's billions for Ukraine
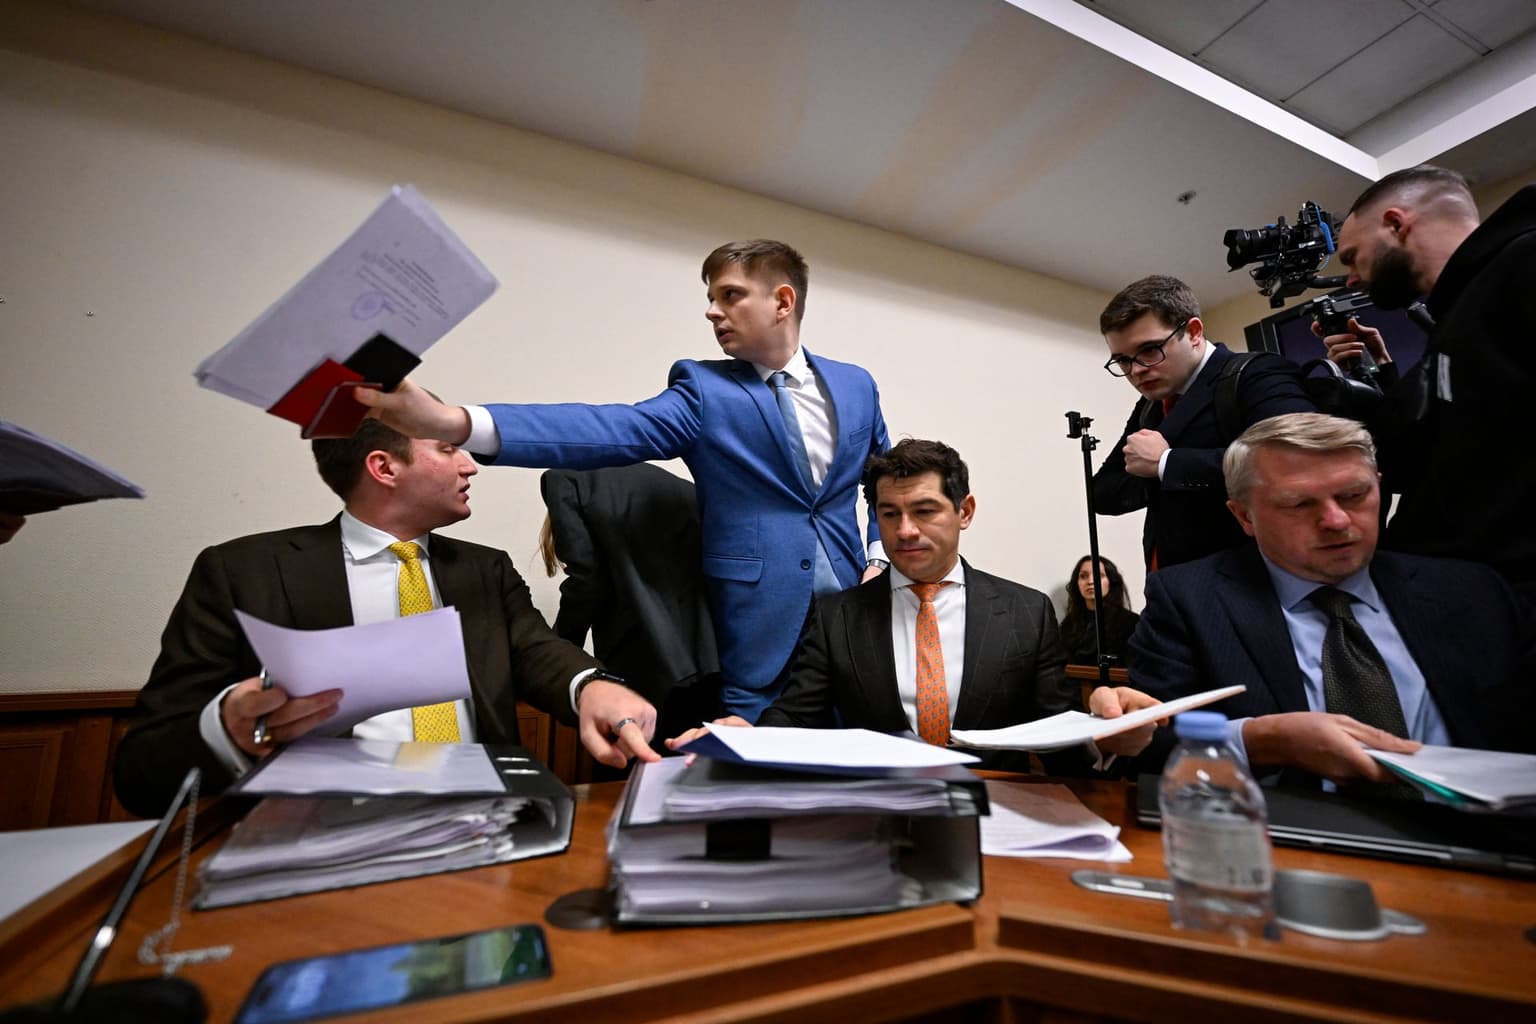
Euroclear financial group lawyers get ready for a preliminary hearing on the Russian central bank’s lawsuit against the Belgium-based Euroclear financial group, which holds Moscow’s frozen international reserves, in the Moscow Arbitration Court in Moscow, Russia, on Jan. 16, 2026. (Alexander Nemenov / AFP via Getty Images)
 on Google
Thomas Venon
Executive Director of the Centre for Development Finance Studies
Clemenceau once said that war is too serious a matter to be entrusted to the military. It may well be that its financing is too important to be left entirely to politicians. The obstacles to using immobilized Russian assets to meet Ukraine's financial needs are presented as mainly technical. The real stumbling blocks are political.
The necessity and the urgency of leveraging the immobilized assets of the Russian Federation stem from a range of reasons.
The size of Ukraine's financing needs, as well as their accelerated timelines, exemplified by a 2027 financing gap of 70 billion euros ($78.6 billion), have brought the possibility of leveraging immobilized assets back to the top of the European agenda.
This is reinforced by the growing fiscal constraints facing those European Union member states willing to help, and by the opt-outs granted to those in central Europe that are not.

Though justice may often seem to the observer of geopolitics to have become an obsolete concept, failing to ensure that Russia pays for Ukraine's war effort would be morally abhorrent, particularly when set against the background of enduring purchases of Russian fossil fuels by European and American allies alike.
The first attempt to put these assets to a more significant use failed in late 2025, when the European Council declined to use them to grant Ukraine a reparations loan. But through optimal structuring and a comparatively small amount of additional political courage, Ukraine's European partners could unlock tens of billions of euros from the already immobilized assets held at the Brussels-based depository Euroclear.
The Centre for Development Finance Studies' April 2026 WOLF paper shows this can be done predominantly on the basis of decisions already made and precedents already tested.
It would be counterproductive, nevertheless, to downplay the very real complexities of the matter.
They include the legal intricacies of the immobilization regime and of Euroclear's regulatory framework and contractual liabilities. There are also real, if difficult to quantify, risks for individual member states, Belgium first among them, and for the credibility of the wider European financial system.
Finally, any solution will require skillful financial engineering to maximize the amounts made available to Ukraine against the constraints the management of these legal, political and economic stability risks creates.
It is not an easy equation to solve. But solved the equation can be.
We must, however, guard ourselves against an incorrect reading of the equation's terms on the basis of a flawed understanding of the materiality of risks and implications for financial systems.
Financial systems are built on trust and predictability. Whilst this does not preclude democratically elected governments from meting out financial justice, there need to be clear rules and transparent procedures to reassure third-party countries that this cannot be done arbitrarily. Their central banks may otherwise think it prudent to move their reserves out of Europe.
While political will is absolutely crucial to set this effort in motion, informed and empowered technical expertise will be required to ensure delivery.

As the European Commission considers the available options, it must push aside unrealistic schemes.
Nothing serves naysayers more than the ability to deride an overly ambitious and objectively unrealistic project. And though their intentions may be laudable, the proliferation of proposals put together with little in the way of relevant banking expertise is unhelpful.
The current process for selecting these options does, in addition, lack transparency.
There is scant evidence that the best available financial and legal expertise is brought to bear inside the halls of power, and by whom. Equally, the lack of public access to crucial pieces of the puzzle, such as the full terms of the G7 ERA loans, prevents experts sitting outside of the decision room from providing fully informed analysis on which civil society and Ukraine's friends can ground their advocacy efforts.
This opacity is a direct threat to the political process. It allows risks to be inflated and opportunities to be overlooked to further political agendas. It potentially enables incorrect technical arguments to serve as fig leaves for political weakness.
It would be naive to expect a process with such wide-ranging geopolitical stakes to play out fully in the open. But it would be irresponsible for the European Commission not to convene an independent panel of legal and financial experts to compile an informed, accurate and fact-based options paper for member states to base their decisions on.
These experts should be provided with the access to information they require to publish their conclusions before European leaders meet again to discuss Ukraine's 2027 financing.
Such a process would reassure the people of Europe and Ukraine that if efforts to make Russia pay for a higher share of Ukraine's defense needs once again falter, flawed technical arguments cannot shield weak political stomachs.
Editor's note: The opinions expressed in the op-ed section are those of the authors and do not purport to reflect the views of the Kyiv Independent.